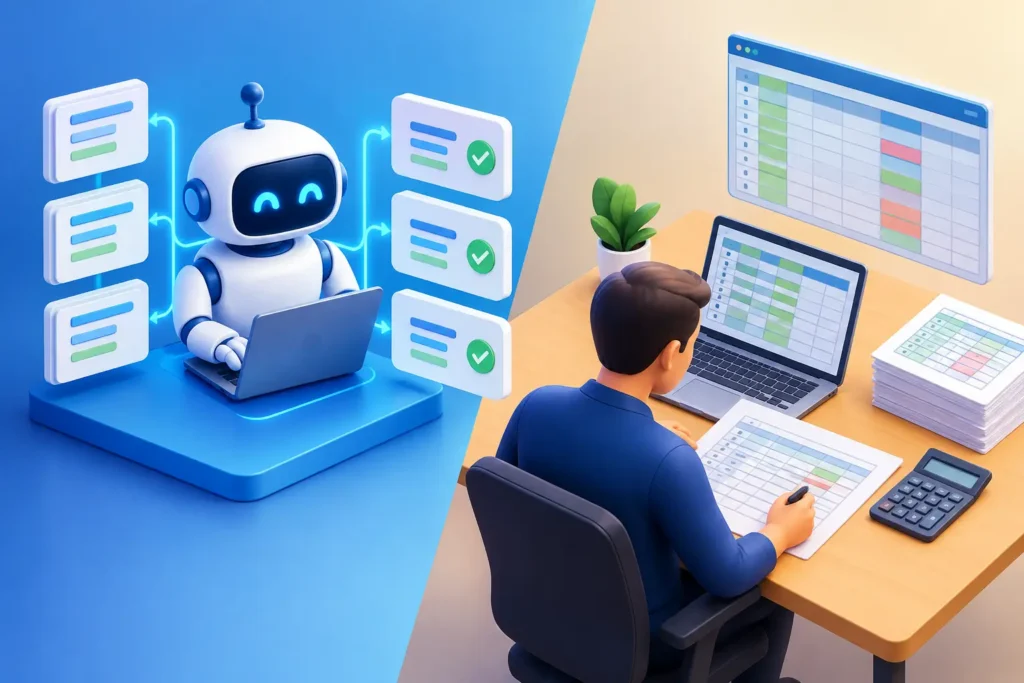
A vendor file can look clean right up until the 1099 deadline exposes the problem: a legal name does not match the TIN, an EIN has been transposed, or a contractor was entered twice under slightly different names. Automated matching versus spreadsheet audits is not simply a technology choice. It determines whether accounts payable and compliance teams find those errors before payment, before filing, or after a B-Notice arrives.
For teams onboarding vendors, validating W-9 information, or managing high-volume 1099 reporting, the spreadsheet approach has a familiar appeal. It is available, flexible, and requires no new workflow on day one. But familiarity is not the same as control. As vendor volume rises, manual audit processes create delays, inconsistent decisions, weak audit trails, and costly opportunities for bad data to move downstream.
Why spreadsheet audits break under real volume
A spreadsheet audit usually begins with an export from an ERP, procurement platform, payroll system, or vendor portal. Someone standardizes names, checks for blanks, searches for duplicates, compares fields to W-9 forms, and flags records that appear questionable. For a small, stable vendor list, that review may be reasonable.
The difficulty is that tax identity data is not clean by default. A business may use a DBA on an invoice, its legal name on a W-9, and a shortened name in an accounts payable system. A simple formatting change can make two identical vendors look unrelated. Conversely, two businesses can have nearly identical names while using entirely different EINs. Spreadsheet logic can highlight differences, but it cannot reliably establish whether a name and tax ID combination is valid for tax reporting.
Manual work also introduces a timing problem. A reviewer may validate a vendor record on Monday, receive a corrected W-9 on Thursday, and never revisit the prior spreadsheet. A formula can be overwritten. A filtered row can be missed. A file version can circulate without a clear owner. None of these are unusual employee mistakes. They are predictable consequences of using a general-purpose grid as a compliance control.
At year-end, the pressure compounds. Teams are asked to resolve thousands of records while payments continue, vendors request corrections, and filing deadlines move closer. The result is often a last-minute review that finds issues too late to prevent operational rework.
Automated matching versus spreadsheet audits: the operational difference
Automated TIN matching applies consistent verification rules to every submitted record. Instead of asking a reviewer to decide whether an EIN and business name look right, the system evaluates the submitted combination against matching data and returns a result that can drive the next step in the workflow.
That distinction matters. A spreadsheet is primarily a review surface. Automated matching is a decision process.
For example, a vendor onboarding workflow can require a valid name-and-TIN match before a vendor is approved for payment. A failed or uncertain result can route the record to an exception queue, request a corrected W-9, or hold the profile for compliance review. The status is tied to the vendor record rather than buried in a separate workbook.
Automation also makes the policy repeatable. Every new vendor is treated under the same rules, whether it enters through a procurement form, an AP request, or a bulk vendor conversion. That consistency is especially valuable for organizations with multiple locations, decentralized purchasing, or several people approving vendor setup.
This does not mean every record should be auto-rejected. Legal-name variations, recent entity changes, trusts, sole proprietors, and incomplete W-9s can require human judgment. The goal is not to remove reviewers. It is to reserve their time for genuine exceptions instead of asking them to manually inspect every record.
What automation catches before it becomes a filing issue
A well-designed matching process identifies more than empty fields. It helps teams isolate the records most likely to create 1099 reporting problems or vendor fraud exposure. Common issues include a name-TIN mismatch, an invalid or incorrectly formatted tax ID, duplicate vendor records, a missing W-9, and a business name that does not align with the information supplied for payment.
The business impact extends beyond tax forms. An unverified vendor can delay a payment run, complicate a merchant or financial account approval, or create a fraud investigation after funds have already left the organization. For BSA, AML, and onboarding teams, verified tax identity information is one useful control within a broader due diligence process.
Automated workflows can also produce a clear disposition for each record: matched, unmatched, needs review, or awaiting documentation. That is far more actionable than a reviewer adding a yellow fill color and a short comment to a row. When management asks how many active vendors have unresolved tax ID issues, a controlled matching process can answer quickly.
Speed matters when onboarding cannot wait
Vendor setup is often treated as back-office administration until it blocks revenue, inventory, services, or a time-sensitive payment. Financial institutions and merchant account teams face an even tighter window. If an account decision takes too long, the applicant may abandon the process or choose another provider.
That is why response time is not a cosmetic feature in TIN verification. A real-time API can return a matching result within the onboarding flow, allowing the system to approve, flag, or escalate the application immediately. Batch processing serves a different need: it can evaluate a large vendor file before a 1099 season, system migration, acquisition, or annual data-cleanup project.
The strongest approach often uses both. Real-time checks prevent bad records from entering. Scheduled batch checks identify older records, changes in source data, and vendor populations that were created before current controls existed.
EINSearch.io supports this model with instant EIN search, high-volume batch processing, and API-based matching. Its large tax ID data index can support fast preliminary responses even when direct IRS availability is constrained, while records requiring IRS confirmation can follow the appropriate validation path. Teams should understand the distinction between a database intelligence result and an IRS match result, then configure their workflow based on the risk of the transaction.
The controls a spreadsheet cannot provide alone
Spreadsheets remain useful for analysis, reconciliation, and ad hoc investigation. They are not inherently a compliance failure. The risk appears when the spreadsheet becomes the system of record for vendor verification without access controls, status history, or consistent exception handling.
A mature process records who submitted the vendor, which source documents were reviewed, when matching occurred, what result was returned, and how an exception was resolved. It should prevent an unresolved record from quietly becoming payable simply because a user copied it to a new tab.
For larger teams, role-based access is equally important. AP users may need to submit or correct vendor data, while tax compliance leaders need authority to clear exceptions. Fraud prevention teams may need visibility into patterns such as repeated bank changes, multiple vendor profiles tied to similar identities, or unusual onboarding behavior. Centralized matching data gives each group a shared record without giving everyone unrestricted edit rights.
When a spreadsheet audit is still appropriate
There are limited cases where a spreadsheet review is enough. A small business with a handful of annual contractors may use one to organize W-9 collection and document follow-up. A one-time cleanup project may also begin with a spreadsheet export before records are submitted for batch matching.
Even then, the spreadsheet should support verification rather than replace it. Use it to assign owners, group exceptions, and track outreach. Do not rely on visual name comparisons as evidence that a TIN is reportable. The more payments, entities, payment systems, or reporting obligations involved, the less defensible a manual-only process becomes.
Build a practical verification workflow
Start at the point of vendor creation. Require a completed W-9 or appropriate tax documentation before payment activation, standardize how legal name and TIN fields are captured, and verify the record before it reaches the payable vendor master. If the result fails, make the next action explicit: obtain a corrected form, perform additional review, or retain documentation supporting the resolution.
Next, address the existing population. Run a bulk review of active vendors, prioritize those receiving reportable payments, and separate obvious data errors from records needing outreach. Then establish a recheck schedule that reflects your risk profile. High-risk or frequently changing vendor groups may deserve more frequent monitoring than stable, long-standing suppliers.
Finally, measure the process. Track match rates, exception aging, duplicate records, missing tax forms, and the number of corrections found before filing. Those metrics show whether the organization is preventing risk at onboarding or merely managing it later under deadline pressure.
The useful question is not whether a spreadsheet is familiar. It is whether your current process can prove that each vendor was validated, route exceptions to the right person, and stop bad tax identity data before it creates a payment or filing problem. If it cannot, the next vendor onboarded is the right place to strengthen the control.