A vendor record can look complete and still be wrong where it matters most: the legal name and Taxpayer Identification Number combination used for reporting. That is why the question is not simply whether to validate a W-9. The operational question is when should IRS matching occur so an incorrect record does not travel through accounts payable, payment systems, and year-end 1099 filing.
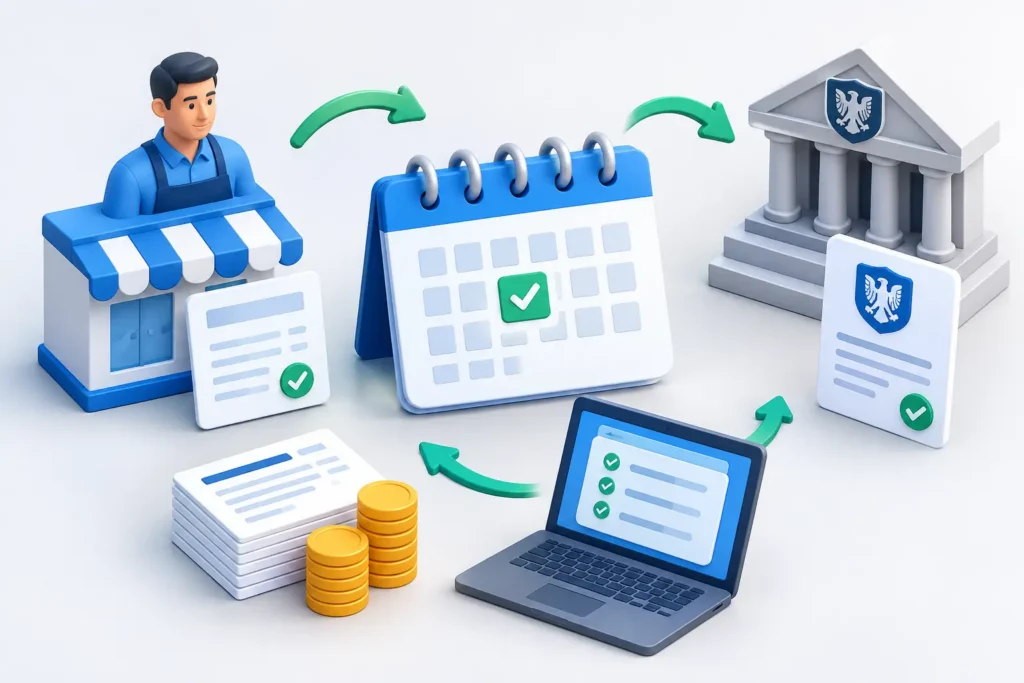
For most organizations, the best answer is early and more than once. Match a TIN before a vendor is activated, again when key tax data changes, and as part of a controlled pre-filing review. The exact cadence depends on vendor volume, payment risk, and how much damage a bad record can create in your workflow.
When Should IRS Matching Occur in the Vendor Lifecycle?
IRS TIN matching should occur before a vendor or independent contractor is approved for payment. This is the point at which the business can still resolve a name-TIN mismatch without interrupting invoices, delaying payments, or creating an exception at filing time.
Accounts payable teams often receive a W-9 after a vendor is already in the system. That creates a common weak point: the vendor is established using invoice information, a trade name, or a contact name, then the tax record arrives later. If the legal name and TIN are not validated before the first reportable payment, the organization may carry that error for months.
A sound control is to require a completed W-9 and TIN verification before the vendor becomes payment-ready. This is especially valuable for new contractors, professional service providers, landlords, legal settlements, marketplace payees, and any supplier likely to receive a 1099-reportable payment.
For high-volume onboarding, timing is even more critical. A real-time verification response can support decisions while a vendor application, merchant account, credit request, or new business account is still in progress. A manual review queue may be appropriate for complex exceptions, but it should not be the default for every clean record.
Match before the first reportable payment
Waiting until January creates avoidable pressure. By then, the vendor may be unresponsive, the business relationship may have ended, or accounts payable may need to research transactions that occurred months earlier. Matching at onboarding gives the vendor time to correct the W-9 and gives your team a documented process for handling an unresolved mismatch.
For vendors who are not initially expected to receive reportable payments, organizations can use a risk-based approach. However, once a vendor crosses a reporting threshold or begins providing services that trigger 1099 reporting, validate the record before the next payment cycle rather than waiting for year-end.
Match whenever tax identity data changes
A new TIN, a revised legal business name, a change from sole proprietorship to corporation, or a new W-9 should trigger another match. Do not assume a vendor name change is cosmetic. A legal entity may have changed, or a payment team may have received a DBA when the IRS record requires the legal name.
Changes in banking information should also prompt a broader vendor review. Bank changes do not automatically mean the TIN is wrong, but fraud attempts often involve altered vendor profiles. Comparing the submitted tax identity, legal name, and supporting documentation helps prevent a payment control issue from becoming a reporting issue as well.
Match before filing 1099s
A pre-filing match is the final quality-control step, not the first time records are reviewed. Run it early enough to correct exceptions before forms are produced and submitted. For many teams, that means beginning reconciliation well before the January filing deadline, after the final regular payment cycle but while vendor outreach is still practical.
This review catches records that were converted from legacy systems, entered before a new onboarding policy took effect, or changed during the year. It also helps isolate the vendors that need immediate follow-up instead of forcing staff to inspect every payee manually.
Why Early Matching Prevents Expensive Rework
A mismatch can lead to an IRS B-Notice after filing. That notice creates a defined follow-up process, vendor communications, documentation requirements, possible backup withholding considerations, and administrative work that was preventable at onboarding.
The risk is not limited to B-Notices. Incorrect tax identity data can delay vendor setup, generate rejected or corrected filings, complicate audits, and weaken fraud controls. For banks, payment platforms, and onboarding teams, an unverified business identity can also create exposure in customer due diligence, anti-money laundering, and Bank Secrecy Act workflows.
Matching early is usually less expensive than correcting late because the record is still close to its source. The person who submitted the W-9 is available. The vendor relationship is active. The payment system has not yet spread the same incorrect information into purchasing, accounting, tax, and vendor master files.
A Practical IRS Matching Schedule
The right schedule is based on risk and operational volume. A small business paying a few contractors can verify each new W-9 at intake and perform one pre-filing review. An enterprise with thousands of suppliers needs automated checks, exception routing, and batch controls.
Use these five trigger points as a practical baseline:
- At initial vendor or contractor onboarding, before activation for payment.
- Before the first payment that may be reported on a 1099.
- When a vendor submits a new W-9 or changes its legal name or TIN.
- When fraud indicators, bank changes, or account ownership concerns require renewed due diligence.
- During a scheduled pre-filing review of all reportable payees.
For ongoing suppliers with stable records, annual rematching may be appropriate as part of the 1099 preparation cycle. Organizations with elevated fraud exposure, frequent vendor changes, or regulated onboarding requirements may choose more frequent validation. The trade-off is simple: additional checks create more processing events, while less frequent checks leave more time for stale or incorrect information to remain in production.
IRS Matching Is Not the Same as a Basic EIN Lookup
An EIN lookup can help locate business information and identify whether a number appears connected to an organization. That is useful for vendor research, lead qualification, and initial fraud screening. But reporting workflows require greater precision: the submitted TIN must match the taxpayer name used for IRS reporting.
A business may operate under a DBA, a shortened trade name, or an invoice name that differs from its legal tax name. Matching the wrong name variation can produce a mismatch even when the EIN itself is real. Accounts payable should retain the vendor’s legal tax name from the W-9 separately from any display name used in purchasing or invoice systems.
This distinction matters when teams attempt to fix records by editing names based on internet searches or invoice headers. Do not guess. Request an updated W-9 when the submitted record does not match, and maintain a clear audit trail of what was received, what was validated, and what corrective action was taken.
Build Matching into the Workflow, Not a Spreadsheet Cleanup
The strongest programs place verification at the point of entry. A vendor portal or onboarding form collects the W-9 data, the tax ID validation step evaluates it, and a mismatch is routed for correction before the vendor reaches payment approval. This reduces duplicate entry and keeps compliance from becoming an annual emergency.
For large files, batch IRS TIN matching for 1099 populations can identify exceptions quickly. For immediate decisions, an API can return a result during onboarding. EINSearch.io supports both operational models with instant search, high-volume processing, and IRS TIN matching designed for vendor validation workflows.
Teams should also define ownership. Accounts payable may own vendor setup, tax may own 1099 filing, compliance may own identity standards, and procurement may own supplier relationships. Without agreed exception rules, a mismatch can sit untouched because every department assumes another team will contact the vendor.
A practical exception process identifies who contacts the payee, how long the record can remain pending, whether payments are held, and when tax or compliance escalation is required. The policy should be strict enough to prevent bad data from moving forward but flexible enough to avoid blocking legitimate urgent payments without review.
Treat Timing as a Control
IRS matching is most effective when it happens before money moves and before tax forms are created. It should be repeated when the taxpayer identity changes and used as a final confirmation before filing. That timing turns verification from a year-end cleanup task into a control that protects vendor onboarding, payments, fraud prevention, and 1099 compliance.
Set the trigger points now, assign an owner for mismatches, and make verified tax identity a condition of a clean vendor record. The next W-9 should enter a process designed to catch errors immediately, not a folder that will be opened when filing season is already underway.